


There Is One Thing ASML’s $400 Million Machine Still Cannot Do. AI Chips Keep Making It Worse.
There Is One Thing ASML’s $400 Million Machine Still Cannot Do. AI Chips Keep Making It Worse.
Omor Ibne EhsanTue, September 15, 2026 at 8:00 PM UTC
0
Inlined / Shutterstock.comQuick Read -
ASML's $400M High NA EUV machine cannot print the largest AI chip designs in a single exposure, and the photomask fix won't arrive until 2031.
NVIDIA and Alphabet must rely on costly multi-exposure stitching for their largest chip designs, adding process steps, overlay complexity, and yield risk.
ASML trades at 57 times trailing earnings, pricing in a fix that analysts target at $2,158 versus today's $1,698 share price.
Just released. Our analysts combed the entire stock market and named the ten best stocks to buy right now, and ASML didn't make the cut. Enter your email to see the names that beat ASML. The report is free. Enter your email and see if any of your stocks made the cut.
Roughly $400 million. That is the widely reported list price of a single high-numerical-aperture EUV lithography system from ASML (NASDAQ:ASML), the most expensive tool in commercial chipmaking and the one AI accelerator designs increasingly need.
Even at that price, current high-numerical-aperture exposure fields cannot print the largest data center chip designs from companies such as NVIDIA (NASDAQ:NVDA) and Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) in a single shot. Existing EUV systems can still manufacture those chips, but only through workarounds that add cost.
The scope matters. Today's tools do make Nvidia's biggest accelerators. What is constrained is printing the very largest single dies in one exposure using the current photomask format.
You are looking at a bottleneck the industry has committed years and billions of dollars to remove, and a stock that has already priced in a lot of that fix. That is the tension of holding ASML today.
Why Stitching Around The Limit Hurts Fab Economics
Chipmakers get around the exposure-field limit by stitching: taking multiple exposures on the same wafer and combining them to form one large design. It works. It also adds process steps, overlay complexity, and yield risk on the most expensive silicon in the world.
Free Report, Just Released
Why Didn't ASML Make The Top 10 List?
24/7 Wall St has helped investors make money for over two decades, and our top analysts just finished ranking the definitive Top 10 Stocks To Buy Now. Not the ten biggest companies. Not the ten everyone is arguing about. The ten best stocks to buy right now.
And ASML didn't make the cut!
The report is free, and you can see why we think each stock is a top investment today.
Enter Your Email and See the Ten →
The fix is a larger photomask format. ASML, Taiwan Semiconductor Manufacturing (NYSE:TSM), and industry partners are developing 12-inch photomasks that would let a high-numerical-aperture system expose bigger chip designs in a single shot, while substantially lifting those systems' productivity.
The timeline is where the pressure sits. ASML has targeted 2031 for a pilot line using the larger format, and TSMC has said full readiness is expected around 2033.
Set that schedule against how quickly AI accelerator designs are growing toward the reticle limit. Customers are not going to pause a training-cluster roadmap for five to seven years while the mask format catches up, so stitching stays in the process, and so does its cost drag.
Advertisement
Meanwhile, ASML's near-term output is capped by physics and clean-room space. Full-year 2026 plans call for around 65 Low NA EUV systems and about 130 DUV immersion systems, with a planned 30% capacity increase for 2027 and another 30% under investigation for 2028.
Market Reaction And Why The Bear Case Is Real
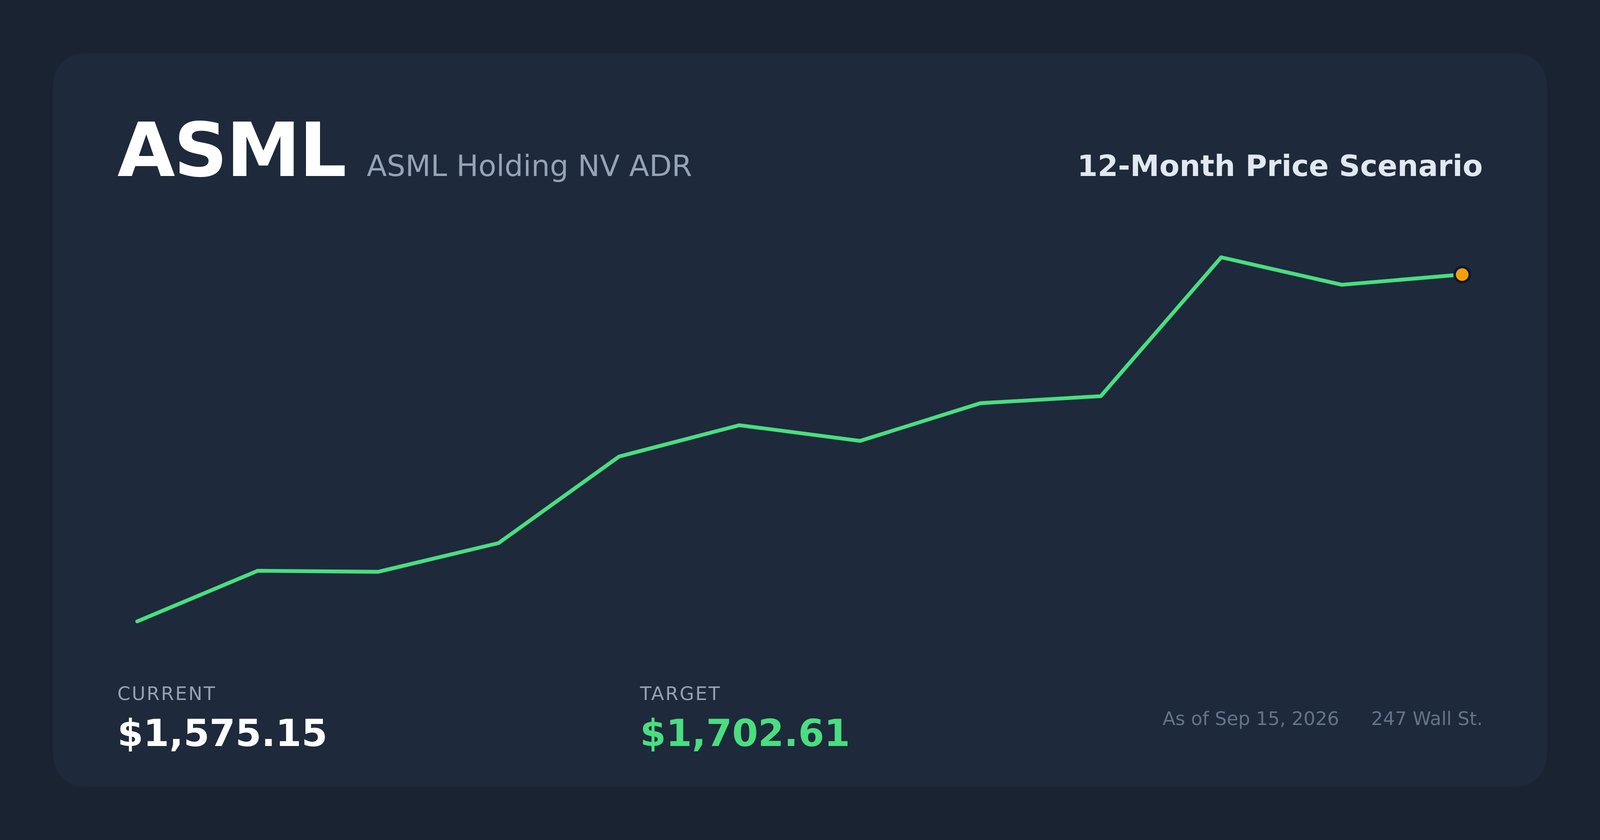
Shares settled at $1,698.30 on September 11, 2026, down 6.17% from $1,810.07 on August 12, 2026. The near-term direction has softened even as the AI narrative has not.
Zoom out and the picture flips. The stock is up 59.52% year to date and 112.6% over the past year, so much of the AI capacity story is already priced in.
ASML Price Scenario — 24/7 Wall St.
The bear case starts with the operating math from the Q2 2026 report. Revenue rose 21.25% year over year to $10.65 billion, yet operating income grew only 10.14% and net income only 9.02%, because ramping capacity costs money before it prints revenue.
Then come the constraints ASML lists in its own outlook: export control restrictions on system shipments to certain customers, tariff announcements, geopolitical developments, and production capacity constraints. None of those go away, even with strong AI demand.
China is the concrete example. Management said previously that China's total net sales in 2026 will decline sharply compared to the very strong business there in 2024 and 2025, and export limits on the most advanced tools remain a live constraint on where the $400 million machine can even ship.
There is also a structural risk that the whole premise loses relevance. If advanced packaging and chiplets keep gaining, customers may not need enormous monolithic dies to hit their performance targets, which would soften demand for the larger-mask solution well before it arrives.
Where ASML Stock Sits
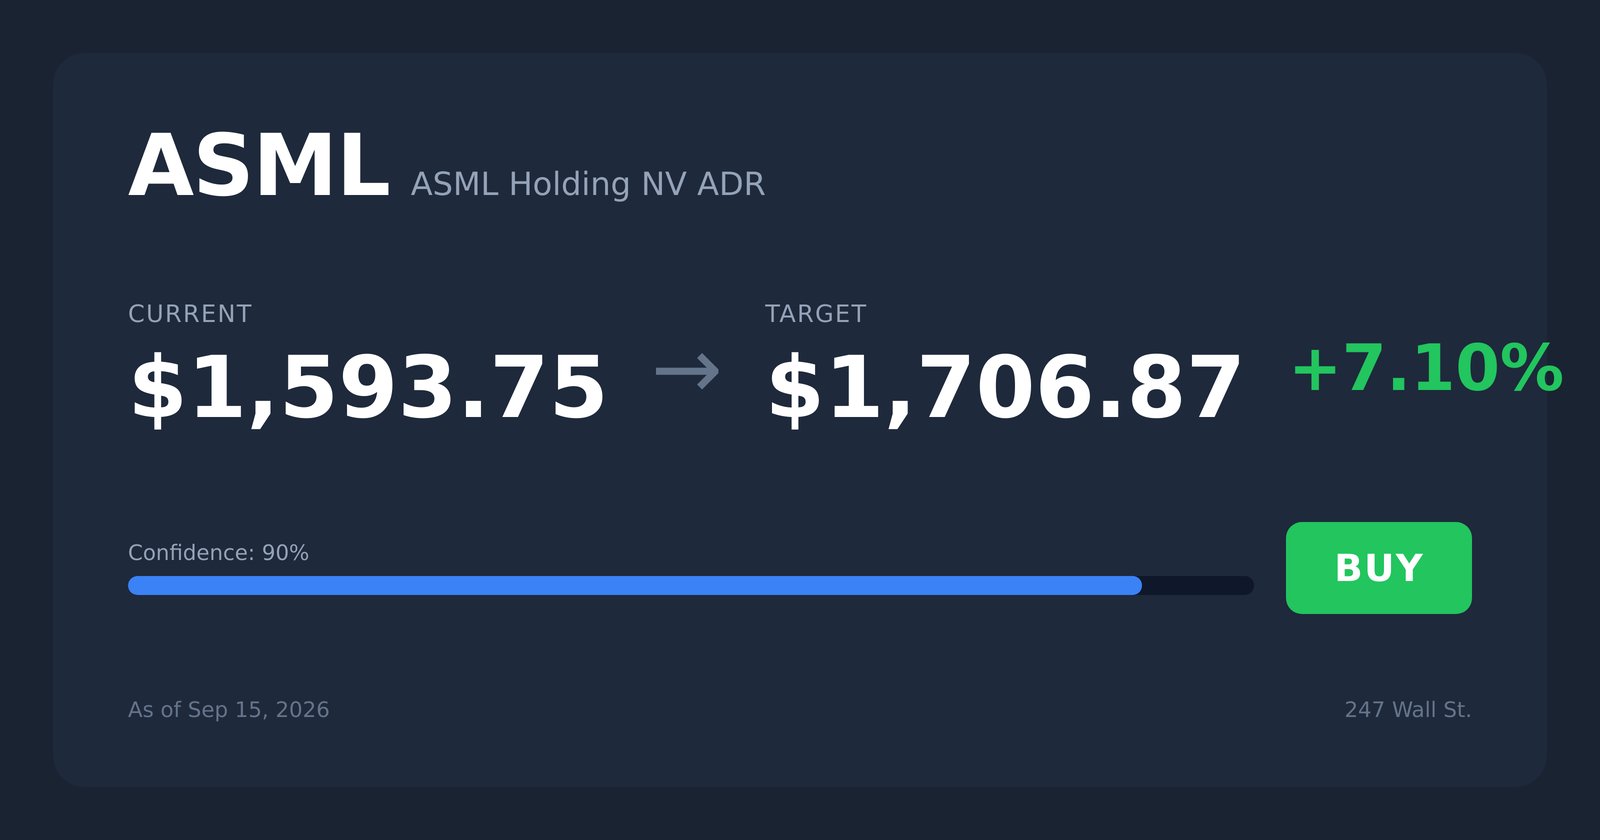
ASML raised its full-year 2026 revenue guidance to EUR 43 billion to EUR 45 billion with gross margin of 54% to 56%, and sell-side analysts carry an average price target of $2,157.87 against the current $1,698.30.
ASML Price Target — 24/7 Wall St.
Shares trade at roughly 57 times trailing earnings and about 28 times forward earnings, with a market capitalization near $652 billion. That valuation assumes the fix arrives on schedule.
CEO Christophe Fouquet framed the setup this way on the Q2 call: "Ongoing AI-related investments and continued progress in AI technologies are driving demand for advanced Logic and Memory chips, further strengthening the semiconductor industry's growth outlook." The demand is real, but so are the shipment caps sitting between that demand and ASML's income statement.
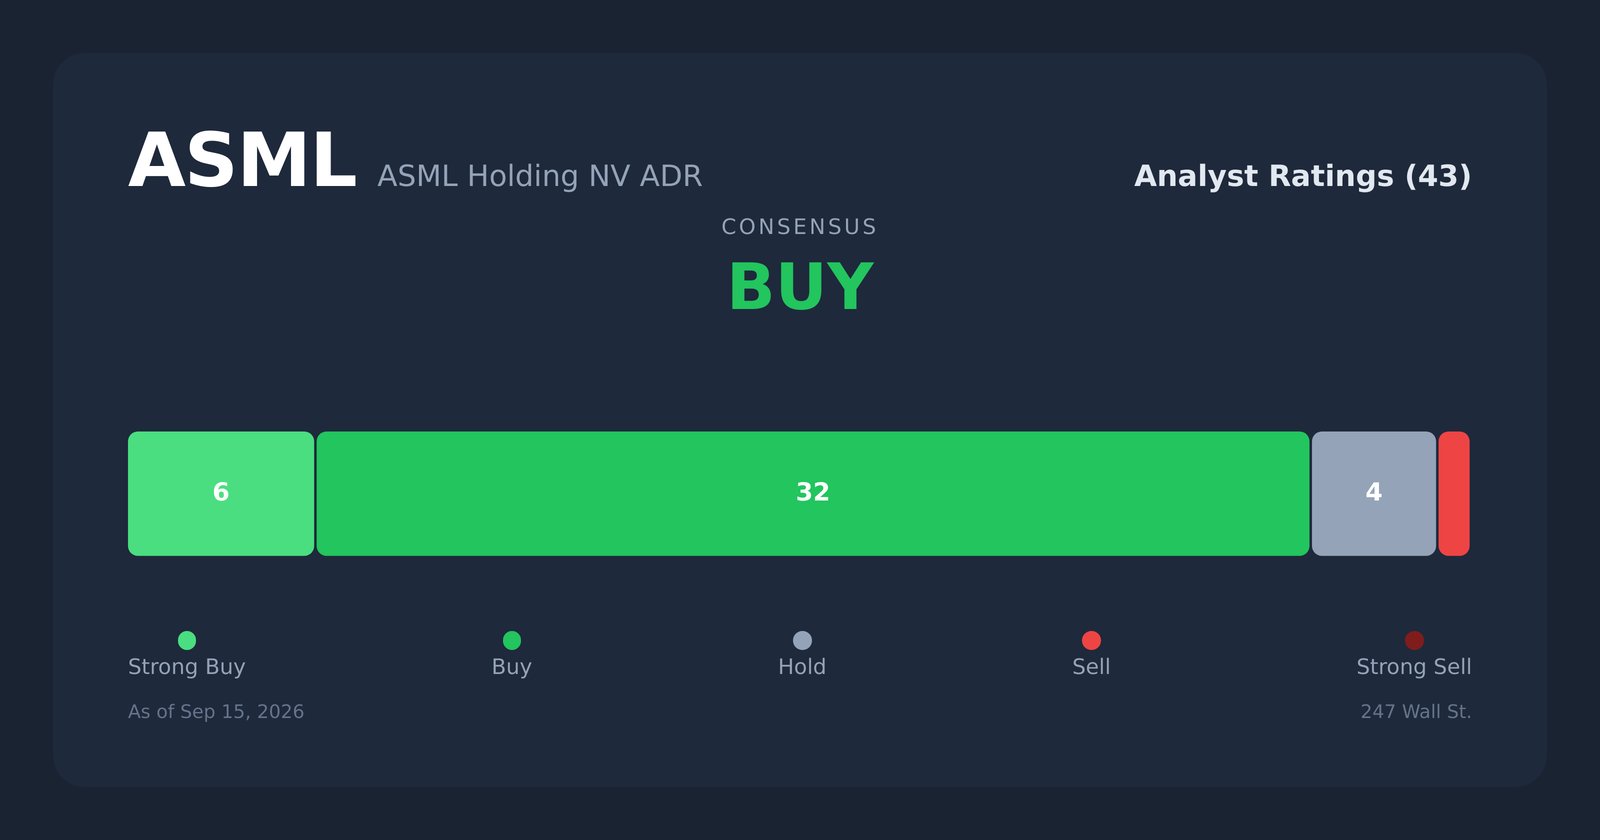
ASML Analyst Ratings — 24/7 Wall St.
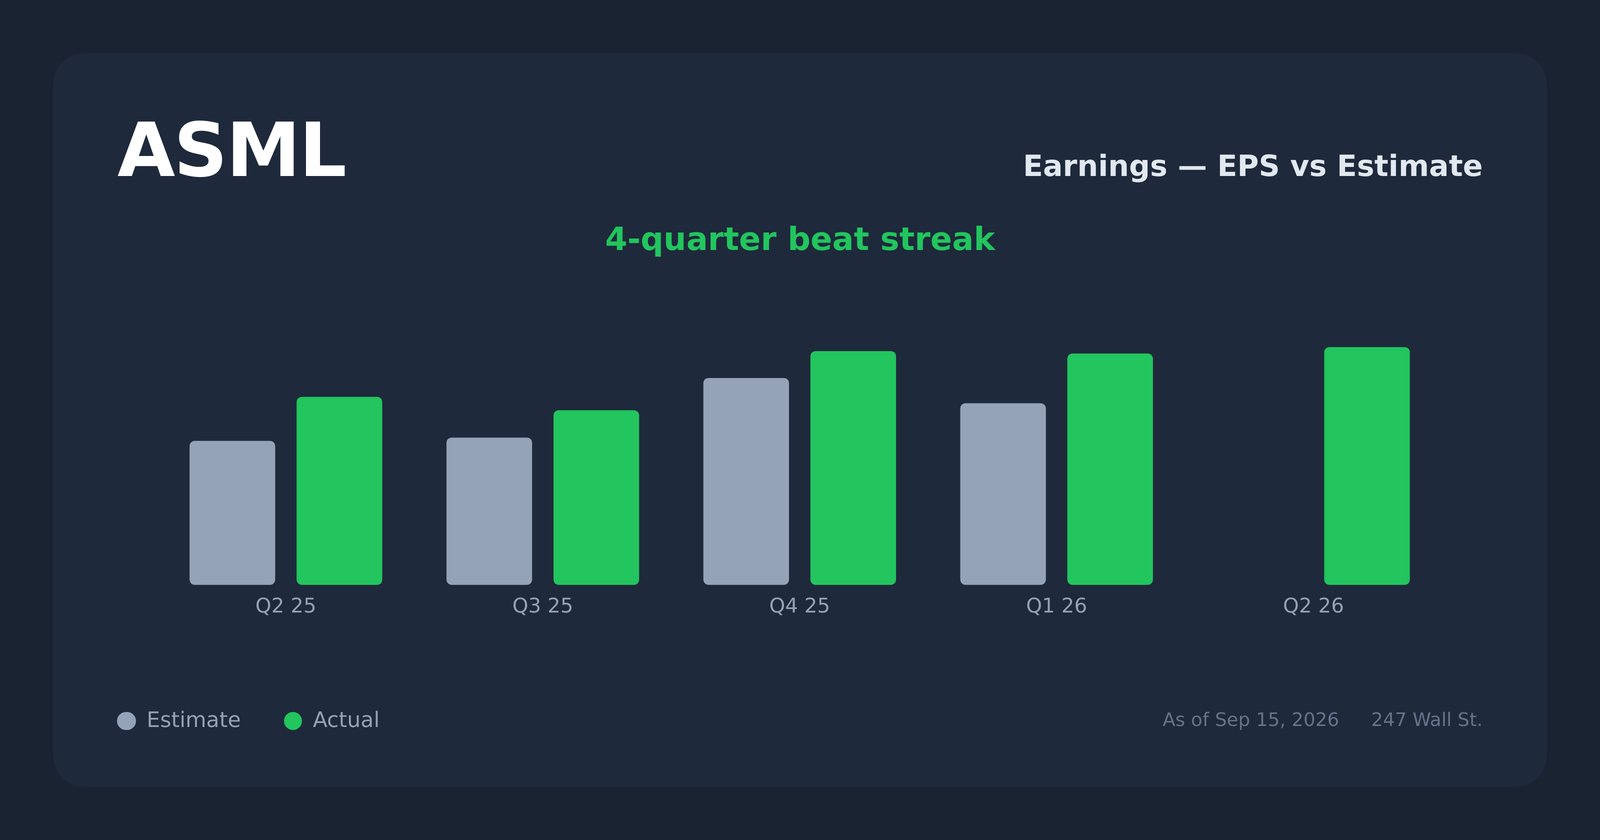
ASML Earnings Explorer — 24/7 Wall St.
The setup looks balanced. The order book, upgrade business, and installed base support the current valuation, although the specific cure for the $400 million machine's single-exposure limit won't arrive until a 2031 pilot line and around 2033 for full readiness, and packaging progress could dilute its value before then.
ASML remains a core semiconductor equipment name trading at a full price. The next event on the company's calendar is Capital Markets Day on June 10, 2027, where the larger-mask roadmap and High-numerical-aperture readiness will get their next serious update.
Got $1,000? Before You Buy ASML, Read This
If you have cash sitting in your account right now, give this two minutes. After more than two decades of helping investors beat the market, our top analysts at 24/7 Wall St. put together a definitive report on the Top 10 Stocks To Buy Today. And ASML wasn't one of them.
They combed the entire market. It's not 10 ideas, not 10 stocks everyone is talking about, it's what their research points to as the 10 best stocks to buy right now, and it's free. Read more here and see which stocks made the list -->>
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
