


Prediction: Oracle Will End The Year at This Price
Prediction: Oracle Will End The Year at This Price
Vandita JadejaWed, September 2, 2026 at 3:00 PM UTC
0
Quick Read -
Oracle (ORCL) trades at just 16x forward earnings despite 93% cloud infrastructure revenue growth and a record $638 billion backlog.
Cash burn of -$23.7 billion and a $20 billion equity raise have dragged ORCL down 23% year to date despite record bookings.
Management's 28% EPS CAGR target through FY2030 and an 87.5% earnings beat probability make a run toward $250 defensible.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Oracle (NYSE:ORCL) has become one of the most polarizing names in mega-cap tech. Cloud infrastructure revenue grew 93% in Q4 FY2026 and the remaining performance obligation backlog exploded to $638 billion.
Yet shares are down 22.75% year to date, closing at $149.12. The question I want to answer: can Oracle end 2026 at $250, or is the market right to punish this stock?
ORCL Price Target — 24/7 Wall St.Why Oracle Shares Are Stuck Despite Record Bookings
Cash burn is doing the damage. Fiscal 2026 free cash flow came in at -$23.7 billion, capital expenditures hit $55.7 billion, and total liabilities now sit at $218.7 billion.
Oracle also plans to raise roughly $40 billion in debt and equity this fiscal year, including a $20 billion at-the-market equity issuance. That is textbook dilution risk. With a beta of 1.72, ORCL swings hard both ways. The stock is off 33.3% over the last year. The recent price action is turning though: up 4.68% in a week and 14.82% in a month. Bulls are trickling back in.
Wall Street Sees 64% Upside. Our Model Sees 44%
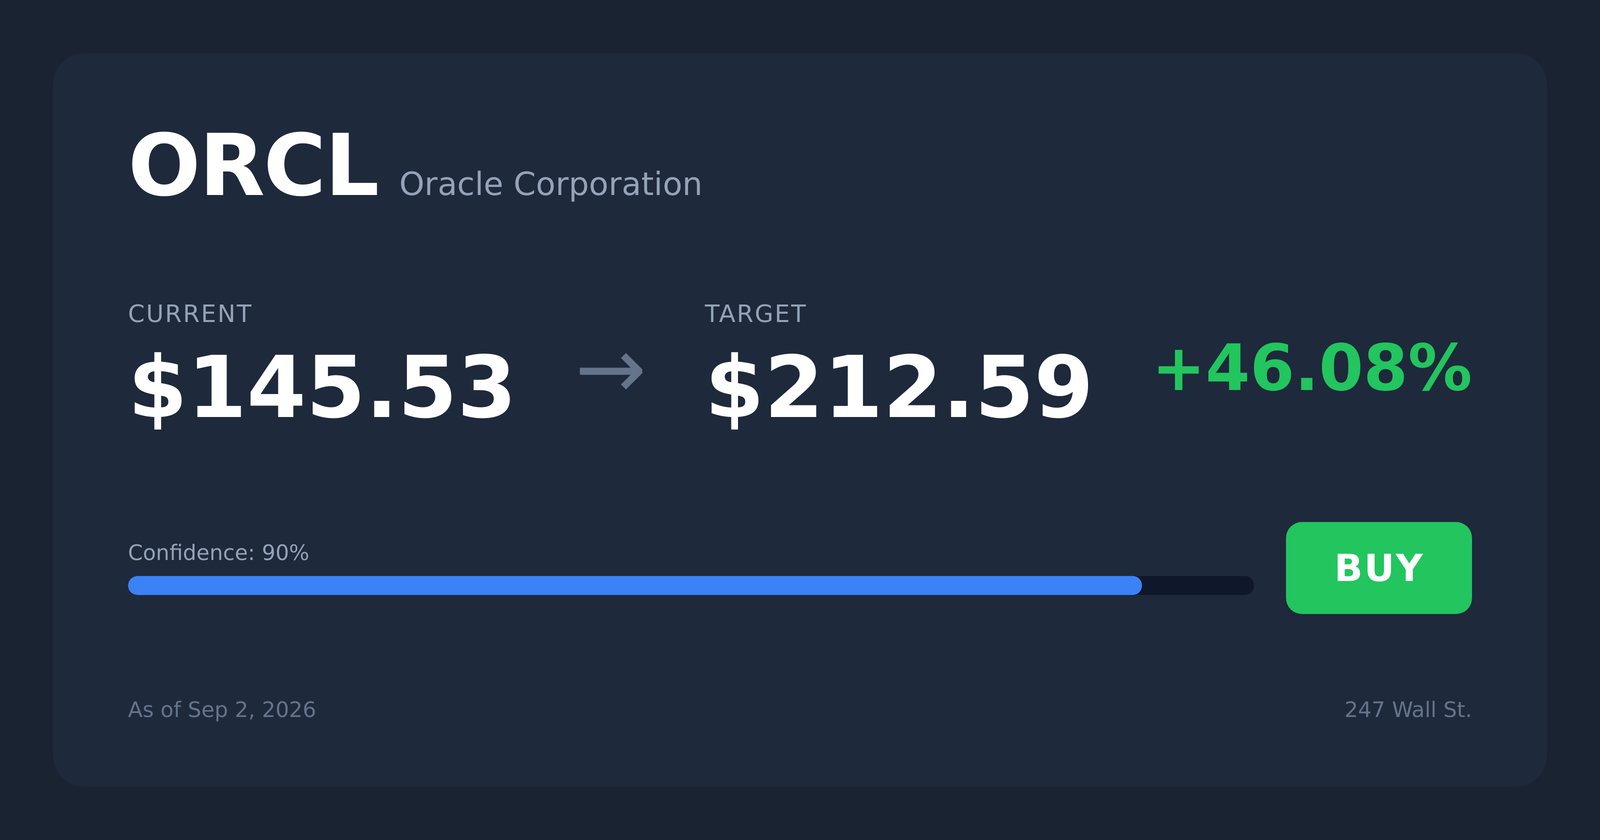
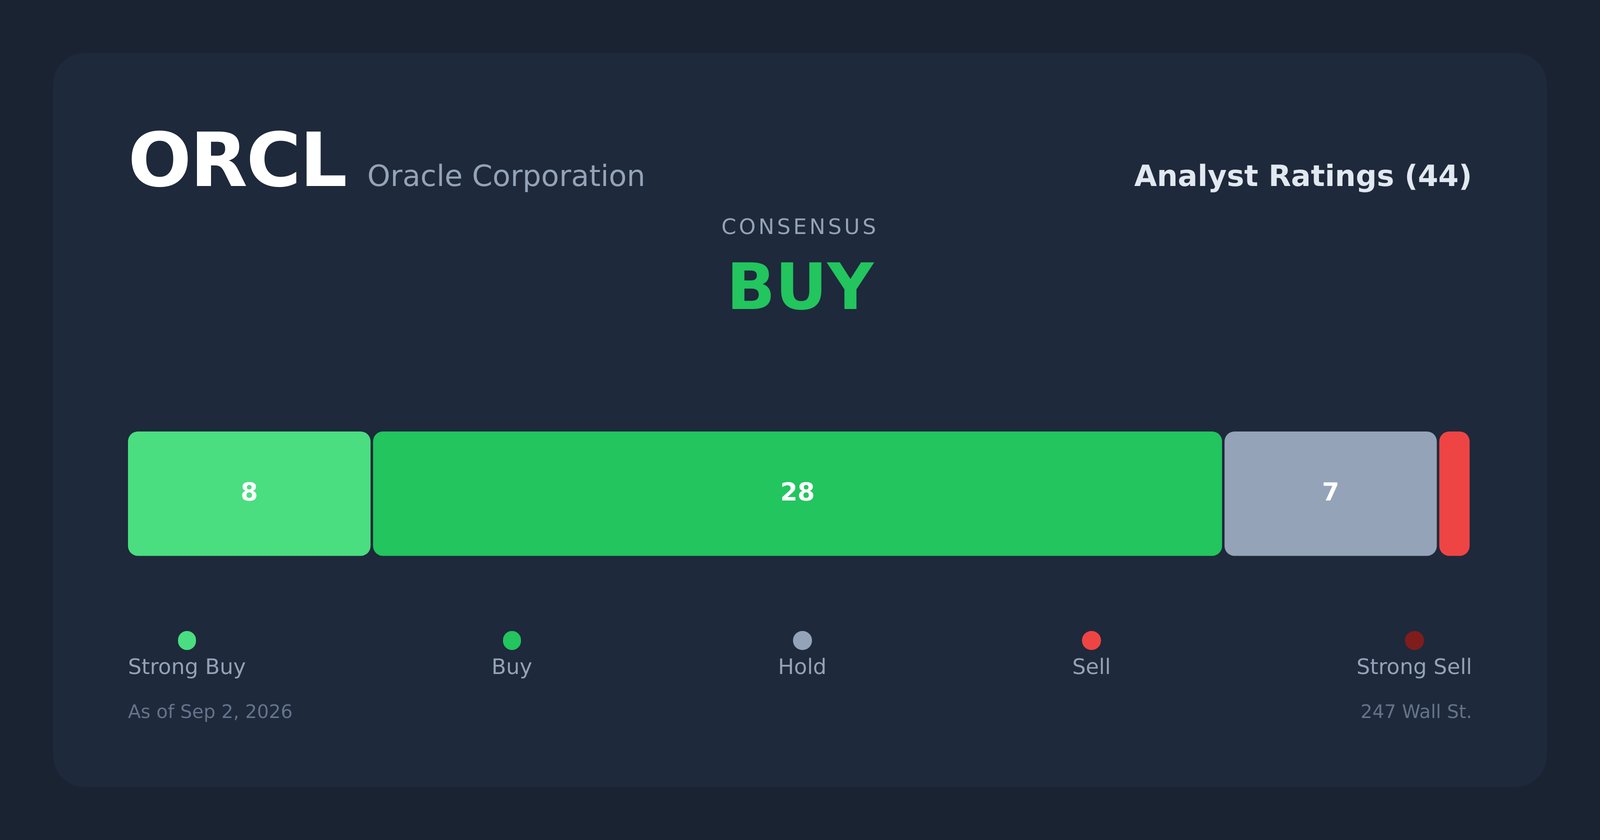
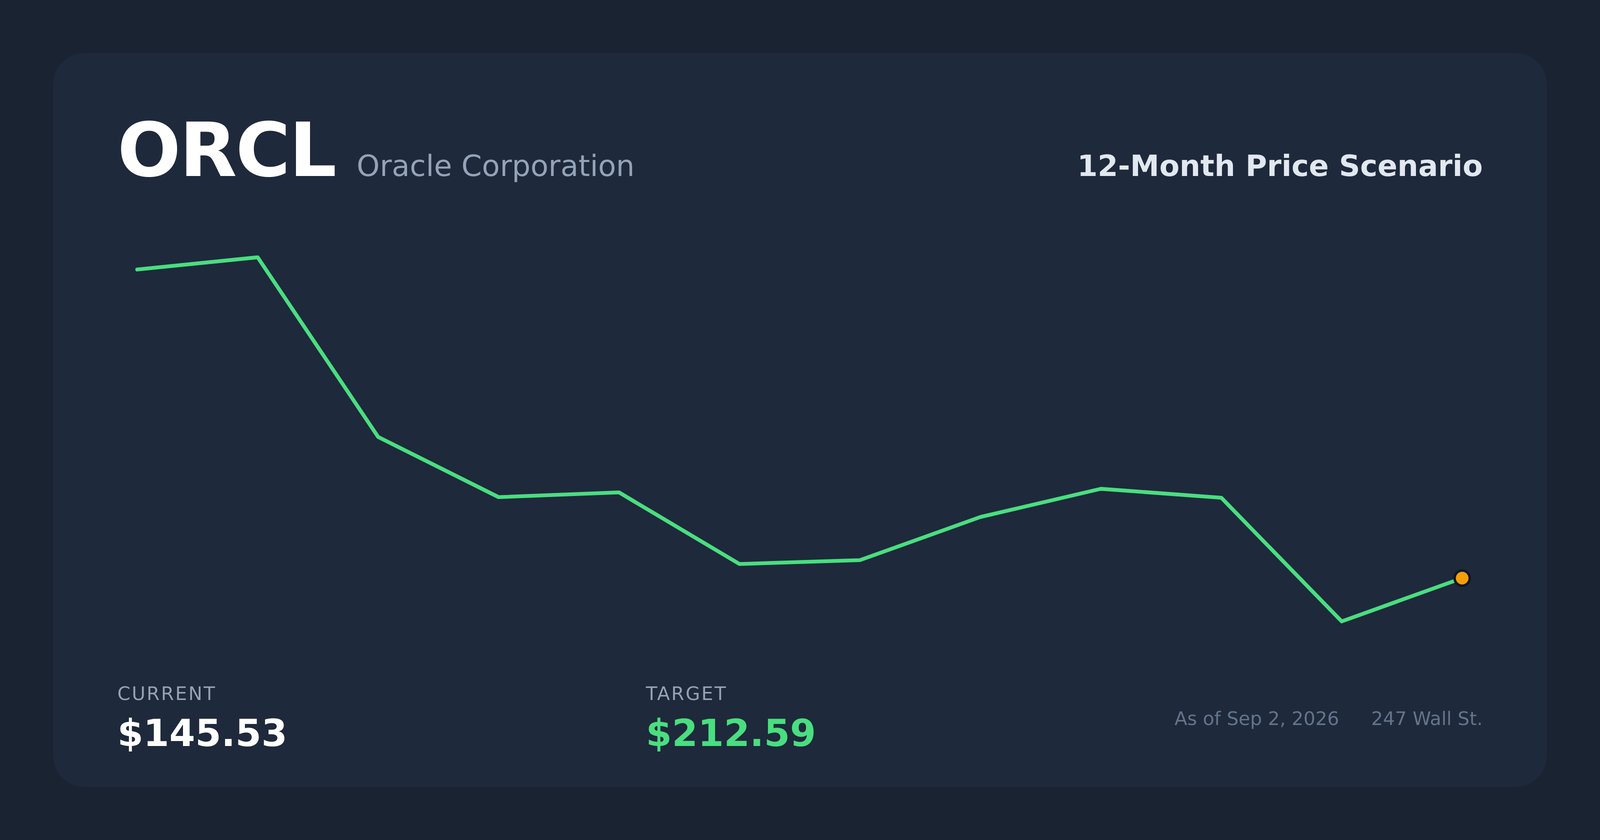
The consensus analyst price target is $244.12, backed by 8 strong buys, 29 buys, 6 holds, and 1 sell. That works out to 84% bullish coverage. Our model lands more conservatively at a base case of $215.24, or 44.34% upside, with high model confidence. The bull scenario reaches $350.43, while the bear case still lands at $181.58.
A $1,000,000 Income Portfolio
If you’ve saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
ORCL Analyst Ratings — 24/7 Wall St.
My take is that Wall Street is right to be aggressive here. Earnings growth of 21.9% year over year, with forward EPS estimates being revised higher across both FY27 and FY28, gives the multiple room to breathe once cash flow inflects.
Path to $250 Per Share
Reaching $250 from today's price of $149.12 would require a gain of 67.7%. With forward EPS of $9.30, a price of $250 implies a forward P/E of roughly 27x. Our base case of $215.24 already implies about 20x, meaning the bold target needs about 7x of additional multiple expansion.
Advertisement
ORCL Price Scenario — 24/7 Wall St.
I think that expansion is defensible. Multi-cloud AI Database revenue jumped 404% in Q4. Global GPU utilization sits at 97.5%. Co-CEO Clay Magouyrk was blunt on the call: "There's still a massively higher demand than there is supply."
Management reconfirmed a long-term 28% EPS CAGR through fiscal 2030. If Oracle beats its September 10 earnings report (Polymarket implies 87.5% odds it does) and RPO conversion accelerates, 27x forward earnings becomes a real conversation. The primary risk: poorly timed dilution from the ATM offering weighs on EPS.
Where Oracle Trades Today Versus Its Earnings Power
On forward EPS of $9.30, ORCL currently trades at roughly 16x. That is cheap for a business guiding to $90 billion in FY27 revenue and $8.05 in non-GAAP EPS.
Shares sit closer to the $114.50 52-week low than the $341.82 52-week high, resting 29% below that peak. Over the past decade the stock is up 319.61%. This valuation reset has created a setup where any clean operational beat gets rewarded aggressively.
Is $250 Realistic? Here's My Verdict
Hitting $250 by year-end 2026 requires a 67.7% rally in four months. That is a stretch, and I want to be upfront about it.
Three things make the setup credible though: the September 10 earnings report as a near-term catalyst, RPO conversion picking up as new gigawatts come online, and confirmation that FY27 EPS growth of 18% stays intact. A stumble on cash flow or a poorly received equity raise would derail everything. Returns at this level shouldn't be expected every year, but we've outlined the blueprint for how Oracle could reach $250 in 2026.
A $1,000,000 Income Portfolio
If you’ve saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
